With two health plans, one pays first for outpatient addiction treatment and the other may cover part of what's left. Coordination of benefits rules decide the order, and they follow the plan holder's relationship to each policy rather than which card you pull out first. Getting that order right before your first session helps you avoid billing surprises later.
Secondary Insurance for Rehab: Which Plan Pays First
Most health plans use a short set of coordination of benefits rules to name the primary plan, and you can usually work out the order yourself before anyone calls an insurer. The plan you hold through your own job comes before coverage you have as a spouse or dependent on someone else's policy. If you're covered by your employer and by your husband's or wife's employer, your employer plan is primary and your spouse's plan is secondary.
Dependent children follow a different rule. When a child is covered under both parents' plans, the "birthday rule" makes primary the plan of the parent whose birthday falls earlier in the calendar year, regardless of the parents' ages. A young adult on a parent's plan until age 26 who also has a plan through their own job generally treats their own employer plan as primary and the parent's as secondary. Divorced or separated parents may be governed by a court order instead, so check the decree if that applies.
Federal coverage has its own rules. Medicare's coordination of benefits guidance explains that whether Medicare pays first depends on factors such as employer size and the reason for eligibility. Tricare commonly is a second payer behind an employer plan, though the details differ by Tricare program, so confirm yours with the plan.
Your insurance card won't tell you who's primary. The most reliable sources are your plan documents, the member services number on each card, and the benefits summary your employer's HR office can send you. Many insurers also send a coordination of benefits questionnaire, and an unanswered one can hold up claims.
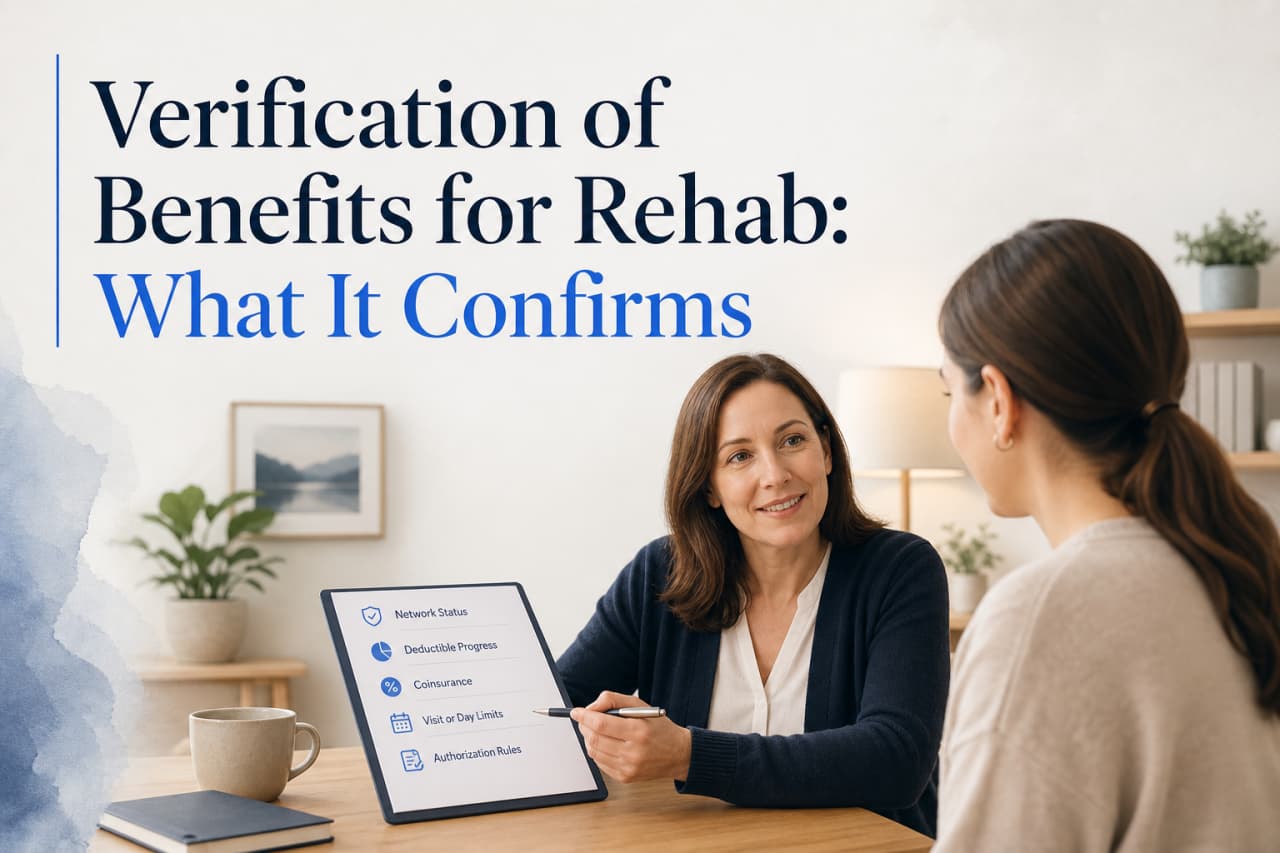
When you call New Hope about IOP or PHP, the admissions team runs free, confidential insurance verification with both plans, and that step is where the order gets confirmed against what each insurer has on file. If your records and the insurers' records disagree, you'll find out before treatment starts. Benefits vary by plan, and verification isn't a guarantee of payment, clinical eligibility, or admission.
This is educational information, not legal or financial advice.
**Selected references**
- Centers for Medicare & Medicaid Services, Coordination of Benefits and Recovery overview: https://www.cms.gov/medicare/coordination-of-benefits-and-recovery/overview
What a Secondary Plan May Cover After the Primary Plan Pays
Once the primary plan processes a claim, it sends an explanation of benefits showing what it allowed, what it paid, and what it left as your share. That leftover amount is what the secondary plan looks at. Depending on its terms, the secondary plan may pay some or all of your deductible, coinsurance, or copay for IOP or PHP.
Secondary plans don't all behave the same way. Some pay up to what they would have paid if they were your only coverage, which can leave you with a remaining balance. Others, under a rule called non-duplication of benefits, pay only the difference between what they'd normally cover and what the primary plan already paid, and that difference is sometimes zero. Because the formula sits in your plan documents, ask each insurer which method it uses before you assume the second plan will close the gap.
A secondary plan also works within its own limits. It generally covers only services it considers covered benefits, so a day of PHP or an IOP session that the primary plan approves isn't automatically approved by the second one. The secondary insurer may ask for the primary plan's explanation of benefits before it pays, and it may apply its own deductible first.
Cost at any level of care depends on the level of care itself, length of treatment, network status, deductible, and coinsurance, and with two plans those pieces get calculated twice. For a sense of how those pieces add up, the costs and payment page explains what shapes your share, and our team can walk through your specific plans during verification.
Here's the order claims usually follow:
- 1The provider bills the primary plan first.
- 2The primary plan pays its portion and issues an explanation of benefits.
- 3The claim, with that explanation attached, goes to the secondary plan.
- 4The secondary plan pays what its terms allow, and you're billed for anything left.
If a bill arrives that doesn't match this order, call both insurers before paying it. A claim sent to the wrong plan first is a common cause of denials, and it's usually fixable once the correct order is on file.
What to Share When Your Benefits Are Verified
Have both insurance cards in front of you, front and back, because the member ID, group number, and claims phone number on each one are what the verification team uses to reach the right insurer. A photo of each card works if you're contacting us by text.
For every plan, be ready to say who the plan holder is. If the coverage comes through a spouse or a parent, that person's full name and date of birth are usually required, since insurers look up dependent coverage under the holder's record. You don't need that person on the line, but you may need their details handy.
Tell the team about any recent change, even one that seems minor. A new job, a marriage or divorce, a birthday that moved a child off a parent's plan, or a plan that renewed in January can all alter which insurer is primary. Insurers often hold outdated records for weeks, and a mismatch at this stage is far easier to fix than a denied claim.
It also helps to mention anything you already know about how the plans interact, such as a coordination of benefits questionnaire you filled out or a letter naming one plan as primary. If the insurers' records disagree with what you've told us, the verification surfaces that before your first session.
Here's what happens after you share this information:
We contact each insurer to confirm which plan is primary and whether coverage is active.
We check what each plan says about the level of care you're considering, whether that's PHP or IOP, including network status and any authorization requirement.
We explain what we found in plain terms, including what may be left for the secondary plan to review.
The process is the same for the Partial Hospitalization Program and the Intensive Outpatient Program, so you can ask for both to be checked at once. The results describe your benefits as the insurers report them, and they're a snapshot of coverage rather than a promise of payment.
When the Two Plans Have Different Networks or Authorization Rules
A provider can be in network with one of your plans and out of network with the other, and that mismatch changes what each insurer pays. New Hope describes itself as an in-network provider that accepts most health insurance, and the carriers named on our site include Aetna, Cigna, Tricare, and several others. Network status is checked plan by plan during verification, so you'll hear about each plan separately instead of getting one blended answer. Our post on in-network vs. out-of-network insurance explains how that status affects your deductible and coinsurance.
Authorization rules can differ just as much. One plan may require prior authorization for PHP and review IOP after a set number of sessions, while the other asks for nothing up front. Approval from the primary plan doesn't carry over, so the secondary plan may want its own authorization before it will pay anything. Ask each insurer three questions:
Does this level of care need prior authorization?
Who has to request it, the provider or you?
What does the plan need to see from the primary plan's decision?
If one plan denies or limits a service, tell the other plan and the admissions team right away. A secondary insurer will often reconsider based on the primary plan's explanation of benefits, and an appeal clock may already be running. Your denial letter lists the deadline for filing one, so keep it where you can find it.
When the plans don't line up, the level of care can still be discussed. Levels aren't a required sequence, so if PHP is approved by one plan and not the other, the team can talk through whether IOP, Evening IOP, or Virtual IOP fits your clinical needs and your coverage better. The licensed clinician makes that call at your assessment, not the insurer's paperwork.
You can start the process on our insurance verification page, and the team will check each plan's network and authorization rules for you.
Keeping Both Plans Updated When Coverage Changes
Insurers don't share records with each other, so a change you report to one plan stays invisible to the other until you tell them both. A new employer, a job loss, a marriage, a divorce, or a child's 26th birthday can each change which plan is primary, and the old order may keep running on one insurer's files long after it stopped being true.
Start with the plan that changed. Ask its member services line to confirm the effective date, then ask whether it needs a new coordination of benefits questionnaire. Then call the other plan and give it the same date, because a claim processed under the wrong order is often paid wrongly or denied, and it can take weeks to reprocess.
Timing matters most when treatment is already underway. If your coverage changes during IOP or PHP, tell the admissions team the same day you learn about it. They can re-run verification against the new records, check whether the new plan has its own authorization requirement, and tell you whether your network status shifts. An authorization on the old plan doesn't transfer, so a gap here is the most common reason a claim for a session that already happened gets held up.
Keep a simple record while both plans are active:
The date of each change and who you reported it to.
The name of the representative and a call reference number, if one is given.
Each explanation of benefits you receive, saved in the order it arrived.
That file is what settles a dispute if the two insurers disagree about who should have paid first. If you also see a plan renew in January, check that its coordination of benefits information still matches what the other insurer has, since renewals are a common point where records reset.
Benefits vary by plan, and what you learn from either insurer reflects your policy rather than a promise of payment. To have both plans checked against your current records, use our insurance verification page or reach the admissions team at 866-806-1027, and they'll confirm the order with each insurer before your first session.