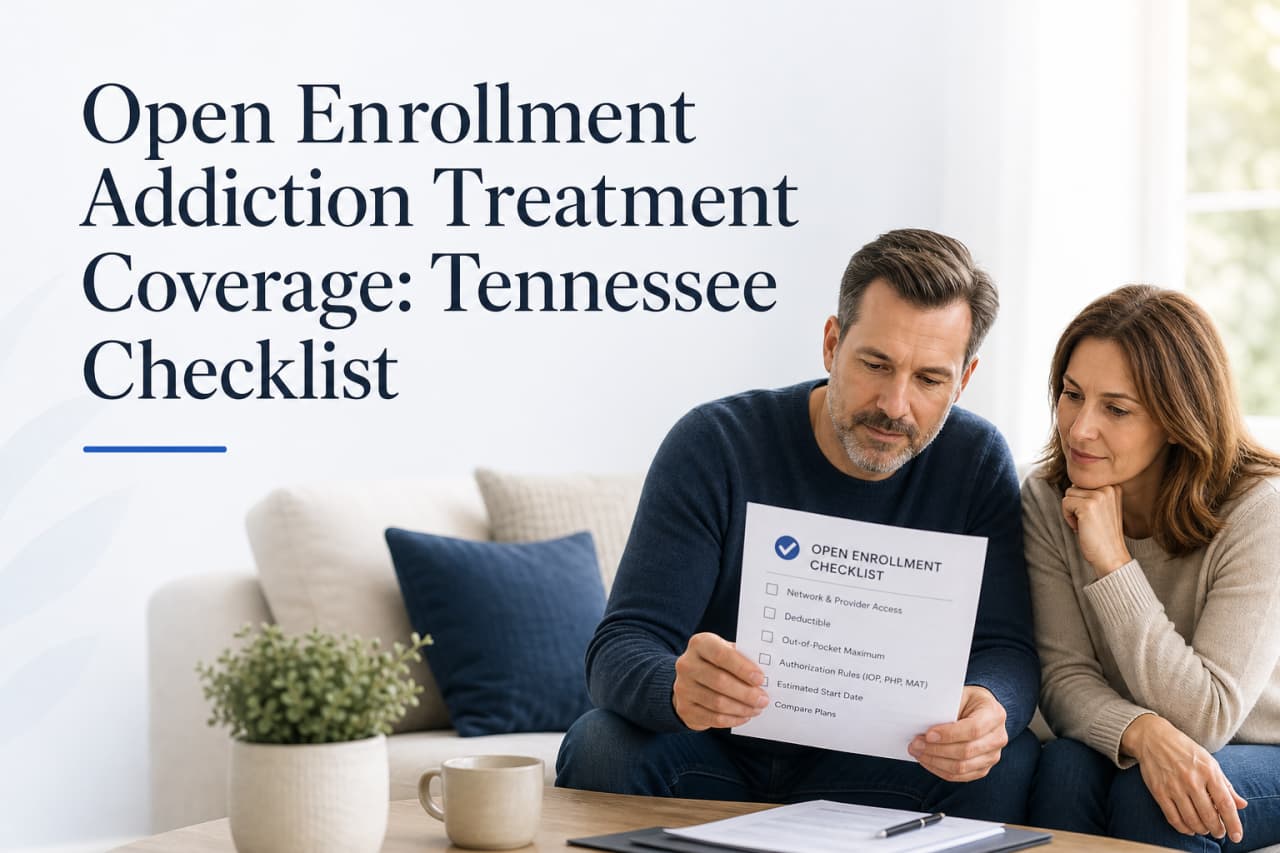
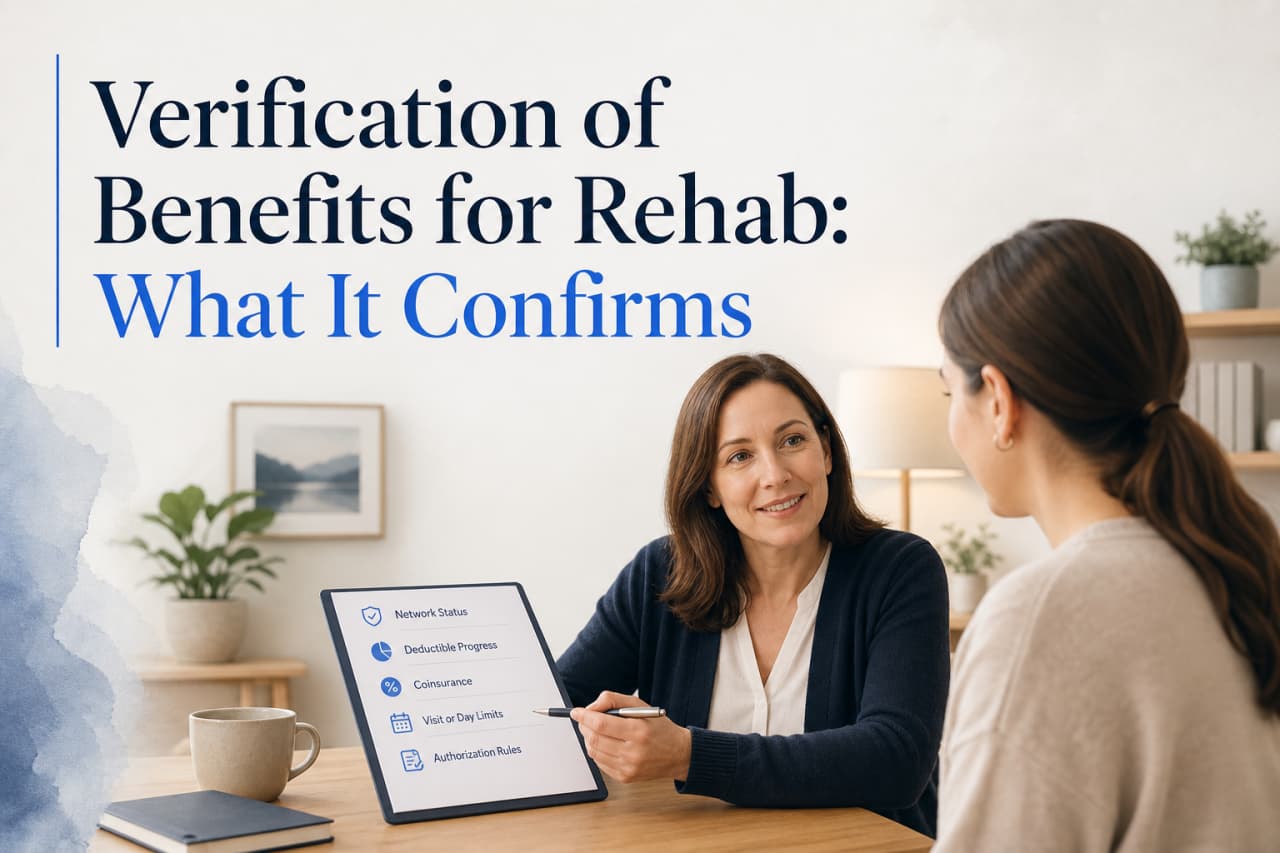
When you're choosing a plan this fall, open enrollment addiction treatment coverage depends on three things you can check before you pick: the plan's behavioral health network, its deductible and out-of-pocket maximum, and its prior authorization rules for IOP, PHP, and MAT. Premiums matter, but they don't tell you what a month of treatment will cost in January. Benefits vary by plan, and the steps below show you what to compare first.
Open enrollment addiction treatment coverage and Tennessee deadlines
Tennessee doesn't run its own health insurance exchange, so Marketplace shoppers here enroll through HealthCare.gov. For most states, HealthCare.gov publishes open enrollment as running from November 1 through January 15, and the date you enroll by decides when your coverage begins. Check the current dates on the site before you plan around them, since the window is set each year and can change.
Employer plans follow a different calendar. Many companies hold open enrollment in the fall, but each employer sets its own window, often just a couple of weeks, and the benefits office or your HR portal will list the exact deadline. If you're covered through a spouse's job, ask them for that date now, because choices usually lock in once the window closes.
Since the window is short, it helps to gather a few things before you start comparing:
- 1The name of your current plan and your member ID, so you can see what it covered this year.
- 2The names of any providers your family member already sees, including a prescriber if medication is part of care.
- 3The level of care a clinician has suggested, such as IOP, PHP, or MAT, because plans often treat these differently.
- 4Your best estimate of when treatment might begin, before or after January 1.
That last item matters more than most people expect. A start date in December and a start date in February can land in two different plan years, and each one has its own deductible.
If you already know a program you'd like to use, you can ask New Hope's admissions team to check your benefits for free and in confidence while you're still choosing. Verification isn't a guarantee of payment or admission, and benefits vary by plan, but it gives you real numbers to compare before the deadline passes.
What to compare in a plan besides the premium
Start with the behavioral health network, because a plan can list a large provider directory and still have few options for intensive outpatient or partial hospitalization care. Look up the program you'd use, not just the insurer's general network, and confirm that the specific level of care is covered at that facility. Plans often keep separate directories for mental health and substance use providers, so check the right one.
Next, find the deductible and the out-of-pocket maximum on the plan's Summary of Benefits and Coverage. A lower premium often comes with a higher deductible, which means you pay more of the early bills yourself. The out-of-pocket maximum is the yearly ceiling on what you pay for covered, in-network care, and it's the number that tells you the worst case for a family facing months of treatment.
Then compare how the plan charges for each level of care. Ask for the coinsurance or copay that applies to outpatient visits, IOP, and PHP separately, since they're often billed differently. A plan that looks affordable for weekly therapy can cost much more for a full-day PHP schedule.
Prior authorization deserves its own question. Ask whether IOP, PHP, and MAT need approval before treatment starts, how long a first approval lasts, and who requests extensions. Programs usually handle the paperwork, but you should know the rules going in.
Finally, look at prescription coverage if medication-assisted treatment might be part of care. Check the plan's drug list, called a formulary, for tiers, copays, and any step requirements. A licensed prescriber decides which medication fits a person at assessment, so you can't know the exact drug ahead of time. Reviewing how the plan treats that whole category still helps.
If a plan's answers are unclear, call the number on the member card and write down the representative's name and the date. You can also pair that call with a free benefits check through our insurance page to see how a plan's terms translate for a specific program.
How the January deductible reset affects treatment that spans the new year
On January 1, most plans start a new benefit year, which means the amount you've paid toward your deductible and out-of-pocket maximum goes back to zero. Someone who starts PHP in November and steps down to IOP in January can meet their out-of-pocket maximum in the first plan year and then begin paying again from the first dollar. Employer plans sometimes run on a fiscal year instead, so check your plan's benefit year dates in its Summary of Benefits and Coverage.
Treatment levels often change right around the new year. A person might finish PHP in December, move to Evening IOP, and continue with outpatient visits well into the spring. Each step down is a different service, and your plan may apply a different copay or coinsurance to it. You'll want to map the likely sequence of care against the calendar, because the reset hits whichever level you happen to be in on January 1.
A few questions help you plan around it:
- 1How much have you or your family member already paid toward this year's deductible and out-of-pocket maximum?
- 2Does the new plan carry over any of those payments? Most don't when you switch plans, so ask directly.
- 3Will a current authorization still be honored after January 1, or does the new plan year require a new request?
- 4Does the care team expect treatment to continue past the first of the year?
The last question is one a clinician can help with. New Hope's levels of care aren't a required sequence, and the care team reassesses before anyone steps up or down, so a realistic timeline usually comes out of the assessment. If you're comparing plans while treatment is already underway, our guide to out-of-pocket maximums and substance use treatment planning shows how to estimate what each plan year could cost.
What mental health parity means for your plan
Under the federal parity law, most health plans that cover mental health and substance use disorder care can't set tougher limits on that care than they set on comparable medical and surgical care. The U.S. Department of Labor explains that this covers financial terms like copays and deductibles, and also limits on visits, days of treatment, and approval requirements. Marketplace plans must cover mental health and substance use disorder services as an essential health benefit, according to CMS.
Parity doesn't guarantee that a plan covers every program, level of care, or provider. It also doesn't mean your costs will be low. It means the rules for behavioral health shouldn't be stricter than the rules for similar medical care, and that's something you can test with a few questions during plan comparison.
Ask the plan to explain, in writing if possible, how it handles prior authorization for IOP and PHP compared with a similar medical service, such as a stay in a skilled nursing facility or outpatient surgery. Ask whether the same copay or coinsurance applies to behavioral health visits as to specialist visits. If a denial arrives, you can request the plan's reasoning and the criteria it used.
Self-funded employer plans and some other plan types follow different rules, so ask your HR office which kind you have. Benefits vary by plan, and these questions give you a way to compare plans before you commit.
Special enrollment periods if you miss the deadline
Missing open enrollment doesn't always mean going without coverage until next year, because certain life events open a Special Enrollment Period. HealthCare.gov lists qualifying events such as losing other health coverage, moving to a new area, getting married, having a baby, or adopting a child. Wanting a better plan for treatment, or learning that a family member needs care, isn't on that list by itself.
The window is short. For most events, you have 60 days from the event to pick a plan, and HealthCare.gov may ask you to upload proof, such as a termination letter from a former employer plan or a marriage certificate. Gather that paperwork as soon as the event happens, since a missing document can delay your start date. If you lose job-based coverage, you can apply even before the last day of that coverage ends, which can help you avoid a gap in the middle of treatment.
Employer plans work differently. A qualifying life event usually gives you a limited window, often about 30 days, to change your elections, but the exact length is set by your plan, so ask HR right away.
If you're already in treatment or about to start, tell the admissions team about the coverage change. They can run a free, confidential check on the new plan through our insurance verification page once you have a member ID. Verification isn't a guarantee of payment or admission, and benefits vary by plan, but it shows you what the new coverage says about IOP, PHP, or MAT before you commit to a schedule.
How to check a specific provider before you enroll
A provider's name appearing in an insurer's online directory doesn't confirm that the program you need is covered under the plan you're about to pick. Directories can lag behind contract changes, and a facility can be in network for one plan from a carrier but not another. So the check has to happen at the plan level, with the exact plan name and not just the carrier's name.
Start by asking the provider's admissions team which carriers and plan types they're in network with, and tell them the plan you're considering. New Hope's admissions process has four steps: initial contact by phone or text, insurance verification, a confidential clinical assessment by a licensed clinician, and treatment planning together. Verification comes second, so you can ask about benefits before any assessment happens. It's free and confidential.
Then call the insurer using the number on the plan's materials. Ask the representative to confirm three things for the specific program: that it's in network for your plan, that the level of care you need (IOP, PHP, or MAT) is a covered service there, and whether it needs prior authorization. Write down the representative's name, the date, and any reference number. If the answers differ from what the provider told you, ask the plan to put its answer in writing.
Keep in mind that a verification isn't a guarantee of payment, clinical eligibility, or admission, and benefits vary by plan. A licensed clinician still decides what level of care fits, and the plan reviews it afterward. If a person needs a level of care New Hope doesn't provide, admissions can discuss referral options.
You don't need to wait until you've enrolled to start. If you have a plan in mind, send admissions the carrier name and the plan's name, and they can check what that coverage says. You can verify your insurance online or call 866-806-1027 to speak with the admissions team.